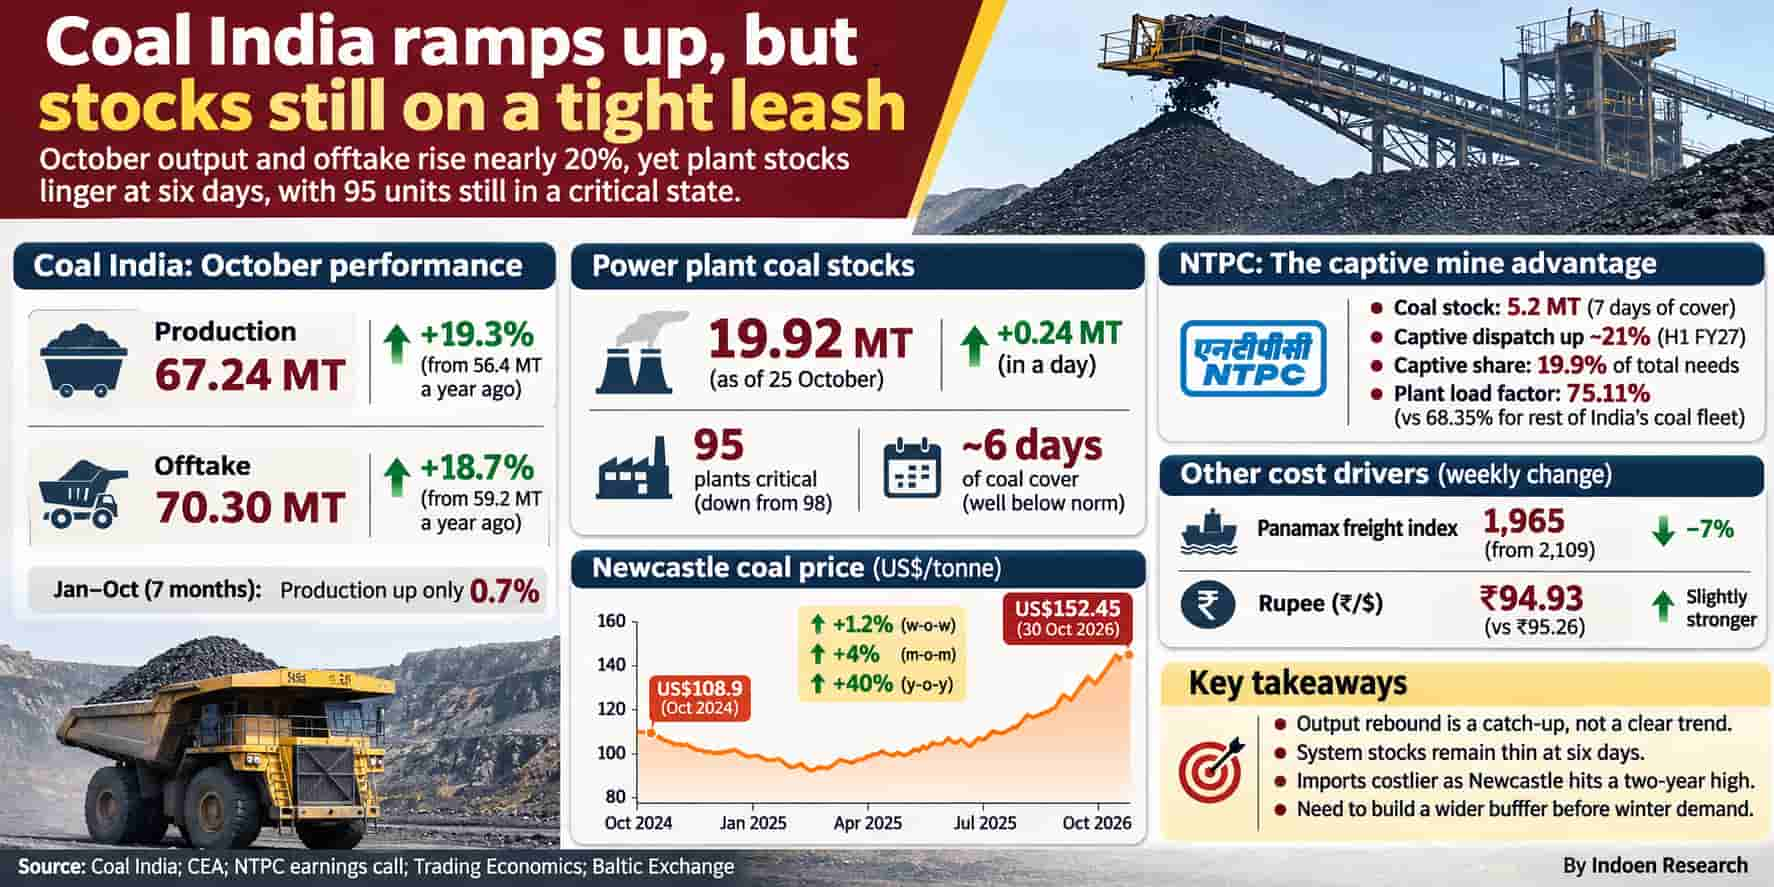
Coal India produced 67.24 million tonnes in October, up 19.3% from 56.4 million tonnes a year earlier. Offtake rose 18.7% to 70.3 million tonnes, company data shows. Dispatches exceeded output, so part of the extra coal came from mine-side stock, not fresh digging.
The jump needs context. Cumulative production for the first seven months is up only 0.7%, according to the same data. October looks like a catch-up month after a wet monsoon, not yet a trend.
“October is a catch-up month. The real test is whether Coal India can hold this pace when the mines are dry and demand stays high,” an analyst tracking Indian thermal coal markets said.
Plant stocks tick up, but the buffer stays thin
Stocks at monitored plants rose to 19.92 million tonnes on 25 October, up about 0.24 million tonnes in a day. The number of critical plants fell from 98 to 95, CEA data reported on 27 October shows. Stocks remain below the 20.44 million tonnes of 15 October and well under a third of the norm. Plants built for imported coal held 2.26 million tonnes, with seven of them critical.
Last week’s analysis showed record dispatch failing to stop the drain. This week brings the first sign that receipts can beat consumption, but only narrowly.
 NTPC shows what an owned mine is worth
NTPC gave the week’s sharpest corporate evidence. On its results call, it said it held 5.2 million tonnes at its stations, enough for seven days. Dispatch from its captive mines rose nearly 21% in the first half, despite supply constraints from Coal India and Singareni, the call transcript shows.
Captive mines met about 19.9% of its coal needs. Its coal plants ran at a 75.11% plant load factor, against 68.35% for the rest of India’s coal fleet.
“Our own mines gave us about a fifth of our coal, and that is what kept our units running while the pipeline was tight,” an executive at a leading thermal utility said.
The insight is that owned coal now works as a fuel-security premium, not only a cost hedge. The limit is scale. Captive output covers NTPC’s own blocks and cannot lift the system average. Indoen has also looked at why coal is being kept on standby for the evening peak.
Newcastle at a two-year high
Newcastle closed at US$152.45 a tonne on 30 October, its highest since October 2024. That is about 1.2% up on the week, 4% on the month and about 40% on the year, market data shows. Constrained Indonesian supply, not stronger demand, is still the driver, as noted in our earlier analysis.
For India, which took about four-fifths of its power-sector imports from Indonesia in August, a firm benchmark makes any import-led stock rebuilding costlier. The government has ruled out mandatory blending, so imports remain a utility choice, not a requirement.
Landed cost: Freight helps only a little
The rupee closed at 94.93 on 30 October after 95.26 the previous day, forex reports show. That left it roughly flat on the week.
Freight softened for coal-carrying ships. The panamax index slid to 1,965 from 2,109 a week earlier, with daily earnings of US$17,686, shipping data shows. That is about a 7% drop.
The saving is small in dollar terms, though. It is dwarfed by the US$1.75 a tonne rise in the benchmark. Landed cost therefore edged up about 1% in rupee terms.
What it means
A rebound in mine output is welcome, but the margin is slim. Seven-month output is up just 0.7%, and plants still hold about six days of coal. The system is one weak week away from slipping again.
Policy has not moved. The Section 11 order on 112 captive plants runs to 31 December. For energy security, the lesson is to widen the buffer, through owned mines, storage and flexible plants, before winter demand arrives.